
Brittny Williams on Turning Spare Change Into PeoplesBank’s Fastest-Growing Digital Bank
Brittny Williams is SVP of Digital Growth & Partnerships at PeoplesBank, where she was hired four and a half years ago to take Zynlo, the bank’s national digital-banking brand, from a one-year-old startup to a business now approaching $300 million in deposits. She also leads PeoplesBank’s fintech partnerships and banking-as-a-service line, applying one filter to nearly everything she builds: “Does this create real relationship depth, not just clicks?”
In this “Beyond the Brief” Conversation, Brittny explains why she doesn’t care about clicks, how she built eight named customer personas from scratch, and why “boutique BaaS” is PeoplesBank’s answer to fintech partnerships that actually fit.
From printing credit cards to running a digital bank
Q: You have an unusual path into banking. Take us from university to where you are today.
Brittny: I went to a state university and got a degree in graphic communications management. I actually wanted to be a math teacher, then a graphic designer, and this program looked like a good lane. My first job was at a printing company, and I ended up at a company called Perfect Plastic Printing, one of the few U.S. manufacturers of secure plastics. I was the salesperson watching Discover, MasterCard, and Visa cards being printed. When I got pregnant and didn’t want to travel as much, I moved into project management for Citibank, our biggest customer, then into strategic marketing, running big names like Office Depot and Brooks Brothers. Digital turned out to be my sweet spot, so I became the digital strategic lead for Macy’s, and later for Best Buy. That’s when I left Citi and came to PeoplesBank. I figured, how hard could it be to jump from credit to consumer banking? There’s crossover, but it’s not as transferable as you’d think.
Zynlo: from a baby brand to a billion-dollar ambition
Q: You were hired to build Zynlo almost from scratch. What does the growth story look like?
Brittny: Zynlo was maybe a year old when I got here. Last year was our best year ever; we basically 10x’d in twelve months. But a few years before that, when rates got crazy, we slow-rolled our own growth to protect the P&L, and nobody accounted for how hard it is to climb back from twenty-five million to a hundred million. It’s actually more expensive than just buying the rate.
Boutique BaaS
Q: You also run banking-as-a-service alongside the consumer brand. How does that fit together?
Brittny: We refer to ourselves as boutique BaaS. We don’t need the sexiest name or to make headlines – we’re here to be good partners and see if the connections make sense. Every BaaS partner wants something different and needs something different, so the whole build-the-engine-and-repeat idea isn’t really a thing here. But it’s fantastic for non-interest income, which every bank wants, because you can’t capitalize the way you could fifteen or twenty years ago.
The named framework
Q: Tell us about the customer segmentation work you recently put in place.
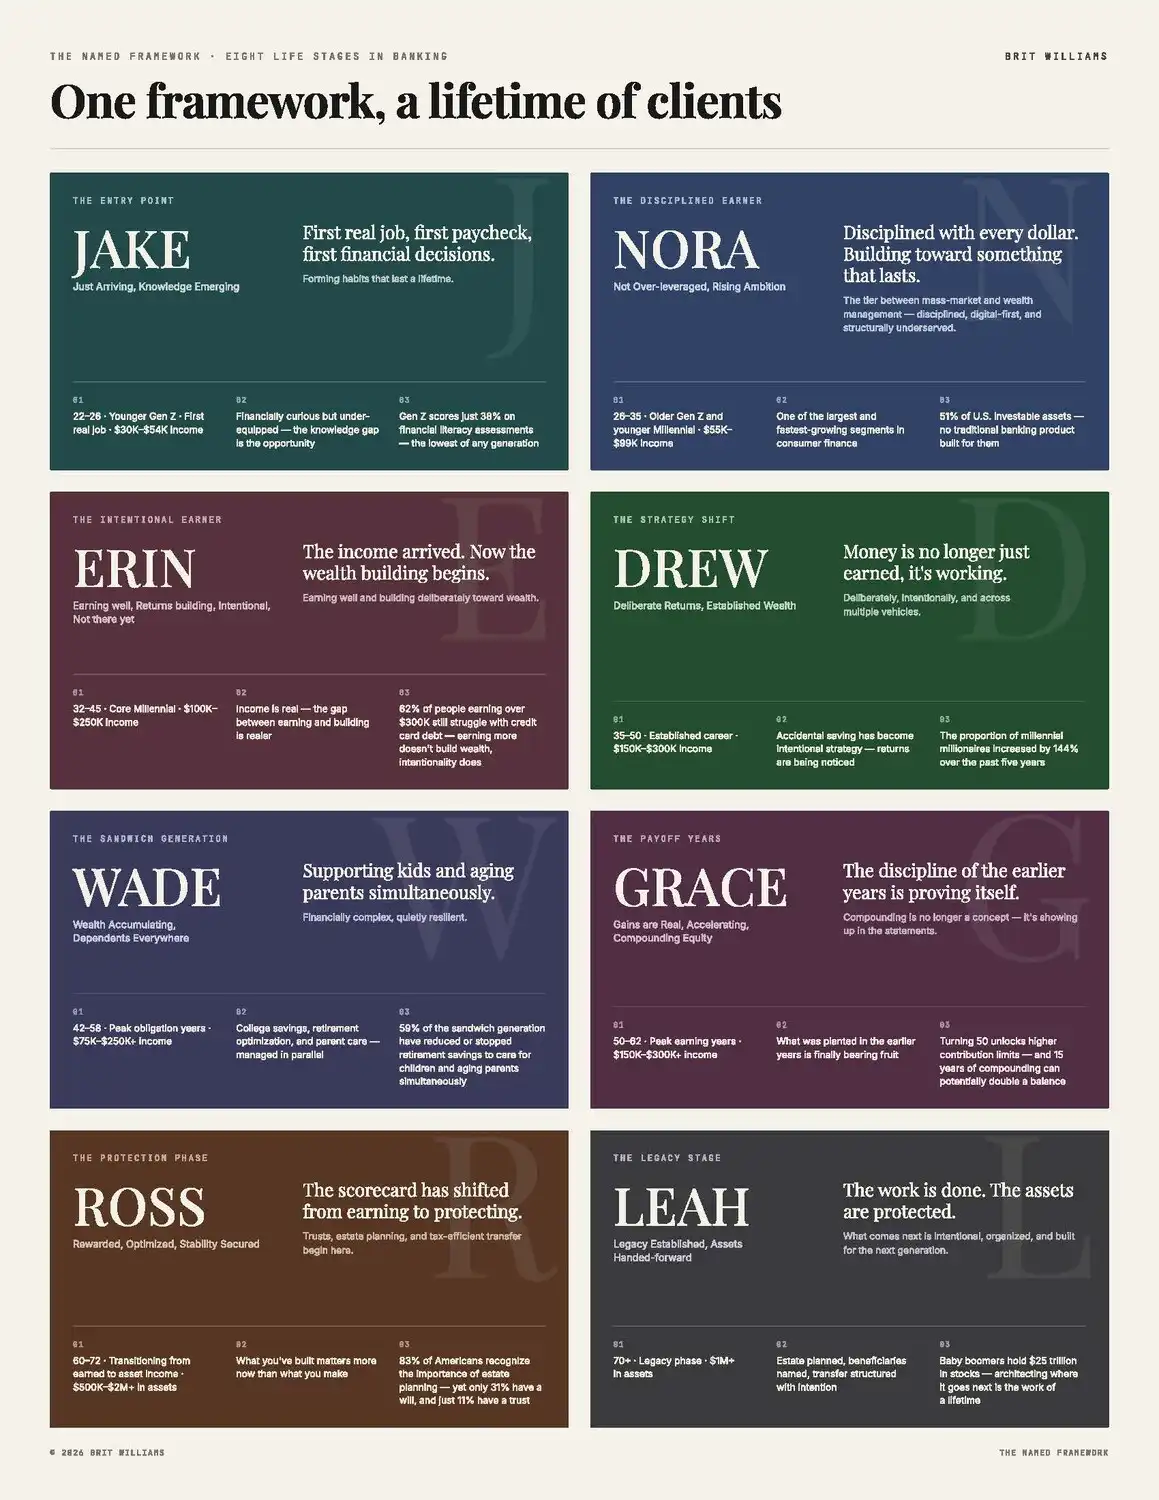
Brittny: I built eight personas and gave every one of them a name, because I can serve you better, Chris, if I know your name and what you actually need, not just that you live in Ohio and you’re sixty. I started with HENRY, high earner, not rich yet, and realized that’s not really our customer. So, I created NORA: not over-leveraged, rising ambition. She’ll listen to our advice and has an emergency fund, but no wealth advisor is calling her. And there’s WADE, my sandwich-generation guy. A lot of people in that group actually stop saving for their kids’ college because they’re supporting their parents, and if you know that, you can help them save differently. It’s clustering by mindset instead of age brackets, so when someone brings me a new product idea, I can literally check it against all eight personas and ask whether it actually fits anyone.
Roundup, match, and what’s next
Brittny: Roundup and Match don’t get enough credit. You round up your spare change into savings, and we match it 100%, so if your average round-up is 39 cents, you just made 78 cents for doing nothing. Nobody else matches the roundup. I don’t care about clicks or even conversions as much as I care about whether five people who saw something became five customers who actually stuck around. Going forward, fraud is the thing eating my time, it’s AI, magnified in every direction, and the P&L cares if you lose more to fraud than you gain in growth. We’re also doing intentional SEO and blogging, so that when someone asks an LLM who the best digital bank is, it can find us on its own.
Brittny Williams is SVP of Digital Growth & Partnerships at PeoplesBank, where she also leads the bank’s fintech partnerships and banking-as-a-service business. Her little-known fact: during the early days of the pandemic, she and her husband sold their house, pulled their kids out of second and fourth grade, and spent a year touring the country in an RV before landing back home in Illinois. Connect with Brittny on LinkedIn and learn more at ZynloBank.com, and PeoplesBank.com.